
Industry News
Biosimilars Pipeline Report Highlights Supply Chain and Manufacturing Gaps Threatening Drug Cost Savings
A new industry report has cast fresh doubt on whether the United States biosimilars pipeline can deliver the cost savings that policymakers and payers have long promised. The analysis, published by the Association for Accessable Medicines, highlights a troubling paradox: while the regulatory pathway for biosimilar approval has matured significantly, the commercial and manufacturing infrastructure needed to bring these products to patients at scale remains under severe strain.
The findings arrive at a critical moment for the pharmaceutical supply chain. Several high-profile biologics face patent expirations over the next five years, creating what should be a golden window for biosimilar developers. Yet the report indicates that many companies in the pipeline lack the manufacturing capacity, cold-chain logistics, and quality systems required to produce biosimilars at volumes sufficient to meaningfully reduce drug costs for US healthcare systems.
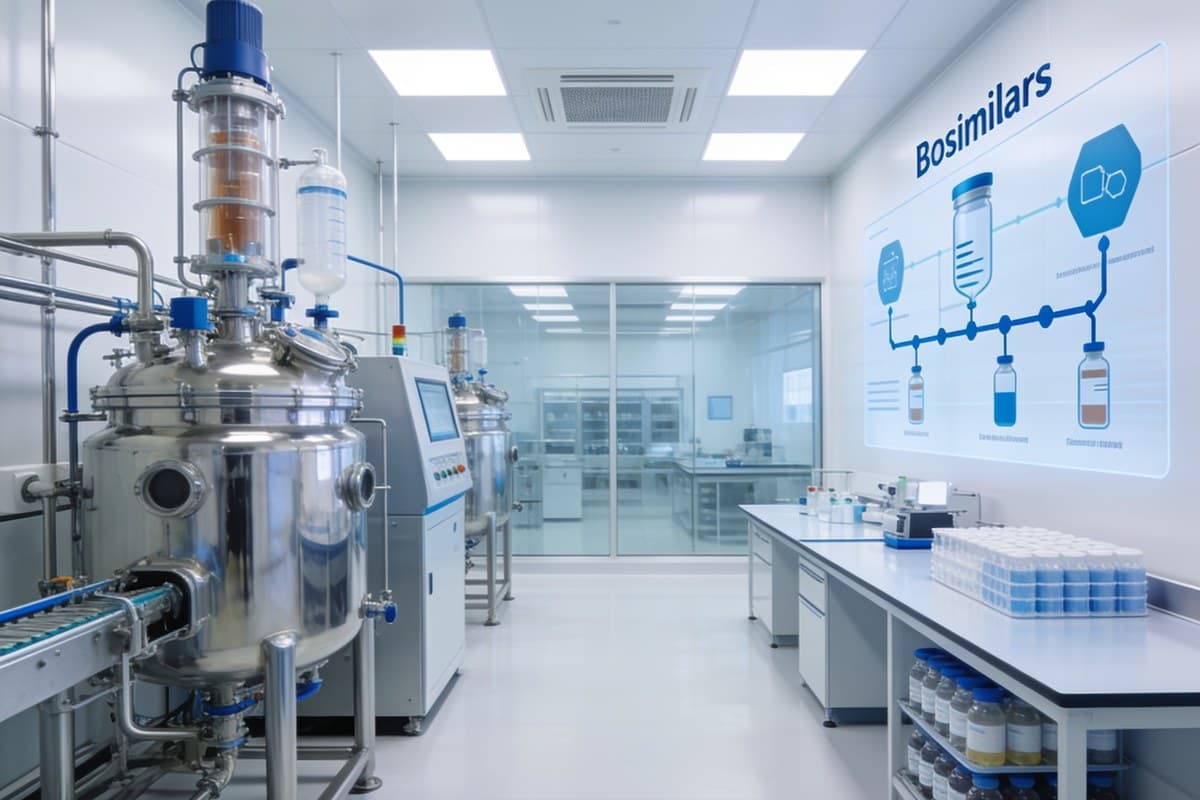
For contract development and manufacturing organizations, this gap represents both a challenge and an opportunity. CDMOs specializing in biologics production are seeing surging demand for their services, but scaling up to meet biosimilar developers' needs requires substantial capital investment in single-use bioreactors, purification suites, and analytical testing capabilities. Many mid-tier CDMOs report lead times of eighteen to twenty-four months for new capacity additions.
The quality requirements for biosimilars add another layer of complexity. Unlike small-molecule generics, which must demonstrate pharmaceutical equivalence through relatively straightforward bioequivalence studies, biosimilars require extensive analytical similarity assessments, functional assays, and comparative clinical trials. Each batch must meet stringent specifications for glycosylation patterns, charge variants, and higher-order protein structure, demanding sophisticated analytical infrastructure that few manufacturers outside the top tier can reliably provide.
Drug pricing dynamics further complicate the picture. The report notes that even when biosimilars do reach market, their pricing often fails to achieve the thirty to forty percent discounts that health systems initially expected. Manufacturers cite the enormous development costs, which can exceed three hundred million dollars per product, as justification for maintaining relatively high launch prices. This dynamic undermines the value proposition that originally motivated payers to support biosimilar adoption initiatives.
The workforce dimension of this challenge deserves particular attention. Biologics manufacturing requires highly trained operators, quality assurance specialists, and process engineers who understand the nuances of mammalian cell culture, downstream purification, and aseptic filling. The current talent pool is insufficient to support the projected expansion of biosimilar production capacity. Companies are investing heavily in training programs and partnering with academic institutions to develop specialized curricula, but the pipeline of qualified professionals remains constrained relative to industry demand.
Raw material supply chains present yet another bottleneck. The cell culture media, chromatography resins, and specialized filtration membranes required for biologics manufacturing are sourced from a concentrated supplier base. When pandemic-era demand spikes or geopolitical disruptions affect these upstream inputs, biosimilar developers face disproportionate impact because they typically lack the purchasing leverage of originator companies with established long-term contracts.
Patient access metrics paint a mixed picture. In therapeutic categories where multiple biosimilars have achieved market entry, such as oncology supportive care and autoimmune diseases, competition has driven meaningful price reductions and expanded treatment access. However, in newer biologics categories where the development timeline is longer and the technical barriers higher, patients may wait years after patent expiry before affordable alternatives become available. This uneven progress underscores the need for targeted policy interventions that go beyond simply approving more biosimilars.
Regulatory harmonization efforts could help alleviate some pressure. The FDA has made strides in streamlining biosimilar approval pathways, and recent guidance documents have provided greater clarity on interchangeability designations. However, international regulatory fragmentation means that a biosimilar approved in Europe cannot automatically leverage that approval for US market entry, forcing developers to run parallel regulatory programs that increase costs and extend timelines.
The competitive landscape is also shifting in ways that may favor larger players. As consolidation accelerates among biosimilar developers, smaller biotechs with promising pipeline candidates increasingly find themselves either acquired by larger generics companies or forced into licensing partnerships. This trend could concentrate manufacturing capacity among a handful of dominant players, potentially creating new supply chain vulnerabilities even as it addresses short-term capacity constraints.
Interchangeability designations represent another frontier that could reshape market dynamics. Products that earn interchangeability status can be substituted by pharmacists without prescriber intervention, a feature that significantly enhances market uptake. Yet the clinical studies required for interchangeability are costly and time-consuming, and only a small number of biosimilars have achieved this designation to date. Industry groups are advocating for streamlined interchangeability pathways based primarily on analytical evidence, a shift that could accelerate market entry and competition.
Looking ahead, the biosimilars market will likely continue to grow, but at a slower pace than many analysts projected five years ago. For pharmaceutical suppliers and CDMOs, the takeaway is clear: demand for high-quality biologics manufacturing services will remain strong, but success will require sustained investment in analytical capabilities, flexible manufacturing platforms, and robust supply chain management. Companies that can offer end-to-end solutions from cell line development through fill-finish will be best positioned to capture value in this evolving landscape.
The broader implication for healthcare systems is that achieving meaningful drug cost savings requires more than regulatory approvals alone. Without parallel investment in manufacturing infrastructure, workforce development, and supply chain resilience, the promise of affordable biologics will remain largely theoretical. Industry stakeholders across the value chain must collaborate to build the capacity needed to turn pipeline potential into patient access.
How can we help you?
Receive insights into the latest events and regulatory updates
Sent directly to your email
Get industry insights and Unibest news here
Contact Us →